Monthly Budget Workbook for Real-Life Spending
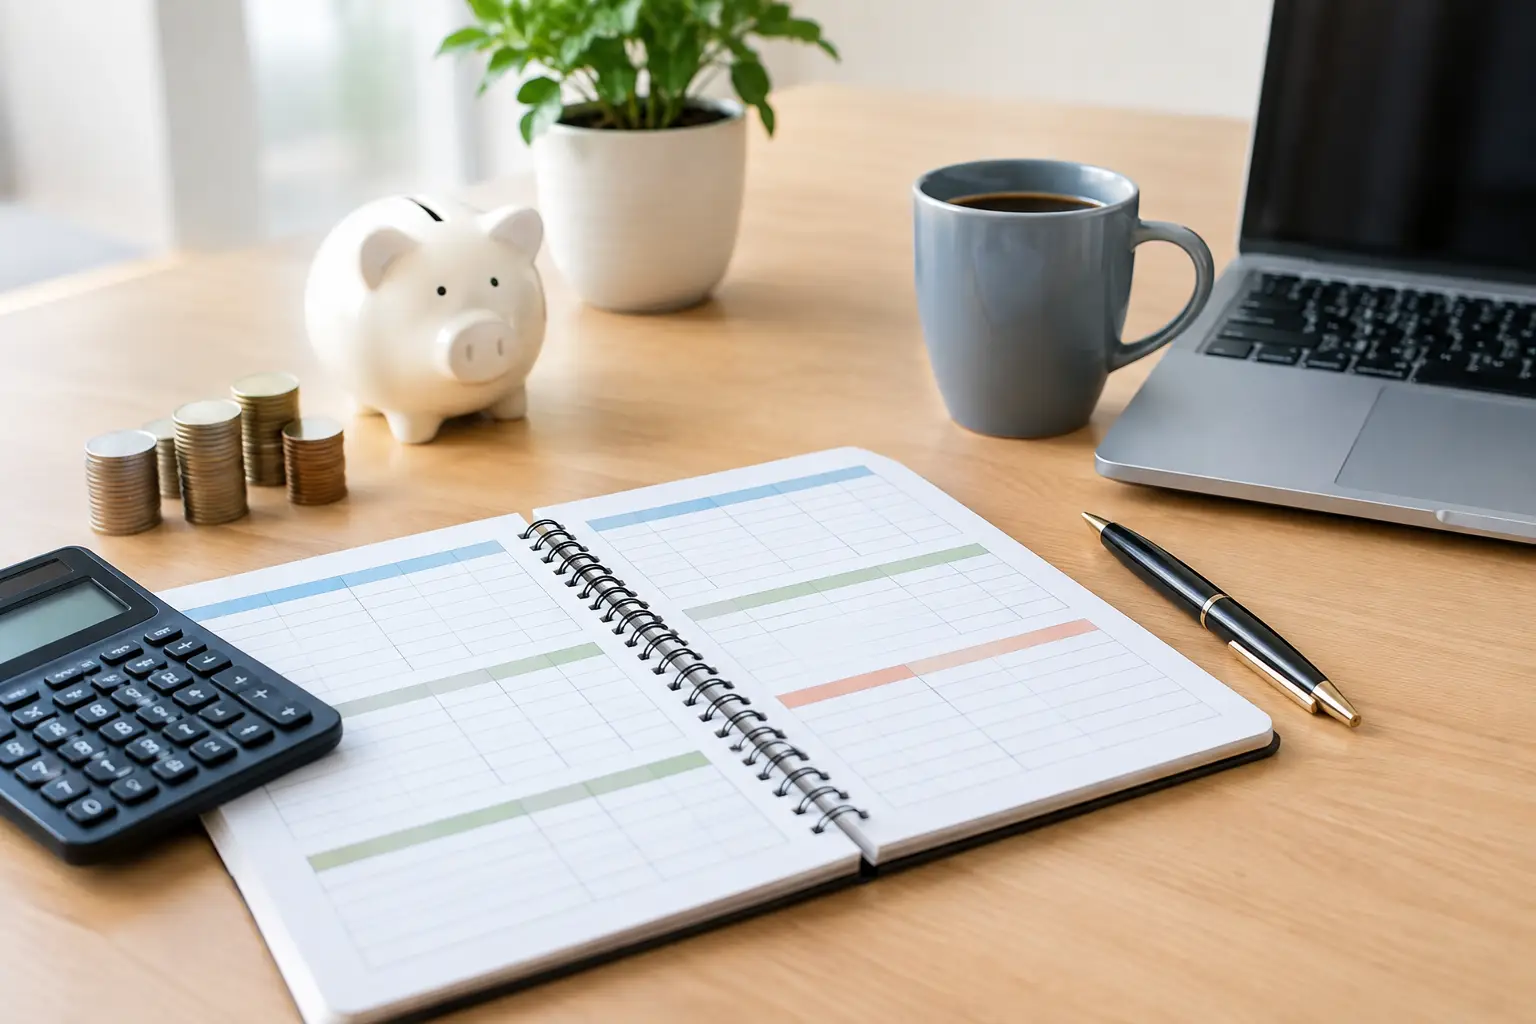
The grocery total is higher than expected, an annual bill hits at the worst time, and somehow the money that looked fine on payday is already spoken for. A monthly budget workbook gives those everyday moments a place to go before they become stressful surprises. It turns your income, bills, spending habits, and personal goals into one clear plan you can actually use.
Budgeting is not about making every purchase feel restrictive. It is about knowing what your money needs to do, deciding what matters most, and enjoying the rest with less second-guessing. Whether you are paying down debt, building an emergency fund, managing a growing family’s costs, or trying to keep a side hustle organized, a workbook can help you make confident choices month after month.
What a Monthly Budget Workbook Should Do
A useful workbook should be simple enough to open regularly and detailed enough to show where your money is going. If it takes an hour to understand or asks you to track categories you never use, it will probably end up unfinished. The best system is the one that fits your real life, including takeout nights, school costs, streaming subscriptions, seasonal expenses, and the occasional unexpected repair.
Start with a page for monthly income. Include your regular paycheck, freelance payments, side-hustle earnings, support payments, or any other money you can reasonably expect. If your income changes from month to month, use a conservative estimate based on your lowest typical month. A larger-than-expected payment can then become extra savings or a debt payment instead of money you already counted on.
Next, separate fixed expenses from flexible spending. Fixed expenses are usually predictable: rent or mortgage, insurance, car payments, phone service, and minimum debt payments. Flexible spending includes groceries, fuel, dining out, household items, personal care, and entertainment. This distinction matters because fixed costs are harder to adjust quickly, while flexible categories give you room to respond when a month gets expensive.
A strong workbook also includes savings and future expenses as actual budget categories. Saving whatever happens to be left over often means nothing is left over. Even a small planned transfer to savings creates momentum and gives your future self a little more breathing room.
Build Your Budget Around Your Actual Patterns
It is tempting to create a perfect-looking budget based on the person you want to be. Maybe that person cooks every meal, never impulse shops, and remembers every birthday gift months ahead of time. Real budgets work better when they are built around the person you are right now.
Review the last one or two months of transactions before assigning category amounts. You do not need to judge every purchase. You are looking for patterns. Perhaps groceries are consistently higher because you pack lunches for work. Maybe rideshares increase during busy weeks, or online subscriptions are quietly taking more than you realized. Numbers are information, not a report card.
From there, set spending targets that feel challenging but possible. Cutting a category from $500 to $50 might look impressive on paper, but it can make the entire plan harder to sustain. A more realistic adjustment, such as reducing restaurant spending by $75 and directing it toward savings, is easier to repeat. Consistency beats a dramatic reset that lasts only one month.
Give irregular costs their own space
Not every expense arrives monthly, but nearly every expense is predictable eventually. Car registration, holiday shopping, birthdays, back-to-school supplies, memberships, pet care, medical copays, and home repairs can all create pressure when they are not planned for.
Use dedicated sinking-fund categories for costs you know are coming. If annual car registration is $240, setting aside $20 per month makes the bill manageable when it arrives. Your workbook does not need a separate page for every possible expense. A short section for upcoming costs and monthly contributions is usually enough.
This approach is especially helpful for households with kids, freelancers with uneven income, and anyone balancing business and personal expenses. The goal is not to predict every surprise. It is to reduce the number of expenses that feel like emergencies.
A Simple Monthly Budget Workbook Routine
A workbook delivers the most value when it becomes part of your routine rather than something you only open after overspending. Choose a budget check-in time that matches your schedule. For some people, that is payday. For others, it is Sunday evening with a coffee and a quick look at the week ahead.
At the beginning of the month, write down expected income, fixed bills, savings contributions, debt goals, and flexible spending limits. Then look at your calendar. Are there birthdays, travel plans, school events, appointments, or renewals coming up? Add them before the money disappears into everyday spending.
During the month, track purchases in a way you will maintain. Some shoppers enjoy recording every transaction. Others prefer a twice-weekly check-in using bank and card statements. Either method can work. The key is to check often enough that you can make adjustments before the month is over.
At month-end, compare planned amounts with actual spending. If a category went over, get curious before changing the number. Did prices rise? Was it a one-time expense? Did the category simply need a more realistic target? This short review is where a budget starts becoming personal and practical instead of generic.
Make Room for Goals Without Forgetting Life
Your budget should reflect both responsibilities and reasons to look forward to the month. If every available dollar goes toward bills and long-term goals, it may feel difficult to stick with the plan. A modest fun-money category can prevent the all-or-nothing spending that happens after weeks of feeling deprived.
The right balance depends on your current priorities. Someone paying off high-interest debt may choose a tighter entertainment budget for a season. Someone who has just started saving may focus first on building a small emergency cushion. A family preparing for a move might put more toward moving costs while temporarily reducing other goals. There is no one percentage that fits every household.
Write specific goals in your workbook so the trade-offs feel meaningful. “Save more” is vague. “Set aside $600 for a family trip by August” or “Pay an extra $100 toward my credit card this month” gives each decision a purpose. When you can see the goal beside the spending category, skipping an unplanned purchase becomes a choice rather than a punishment.
Keep the layout easy to use
A monthly budget workbook should reduce mental clutter, not create more of it. Look for a layout with clear income, bills, spending, savings, debt, and monthly review sections. Plenty of blank space is helpful for notes, changing priorities, and expenses that do not fit neatly into a preset category.
Digital workbooks are especially convenient for shoppers who want to get started right away. You can download, print, reuse pages each month, or keep records in one organized place. At Ultimate Offering Point, practical digital resources are designed for people who want straightforward tools without needing a complicated financial system.
Remember that a workbook is a guide, not a contract. If a new expense appears, update the plan. If your income changes, revise the categories. If you miss a week of tracking, begin again at the next purchase instead of waiting for a new month. Progress comes from returning to the plan, not from filling in every line perfectly.
The most helpful budget is the one that helps you sleep better, spend with intention, and see your next step clearly. Open your workbook before the month gets busy, give every dollar a purpose, and leave a little room for the life you are building along the way.

Leave a comment